
Pakistan is aggressively diversifying its sovereign borrowing framework by targeting additional yuan-denominated “panda bonds” in China and evaluating the issuance of yen-denominated “samurai bonds” in Japan. The strategic pivot toward East Asian capital markets marks a calculated macroeconomic attempt by the heavily indebted nation to broaden its financing arteries following a prolonged period of economic instability.
Speaking in an interview with Nikkei Asia, Federal Minister for Finance and Revenue Muhammad Aurangzeb confirmed that Islamabad intends to establish itself as a regular sovereign issuer within China’s domestic capital ecosystem. The policy shift directly follows the country’s inaugural Chinese bond execution in May 2026, which successfully raised 1.75 billion yuan—equivalent to approximately $261 million.
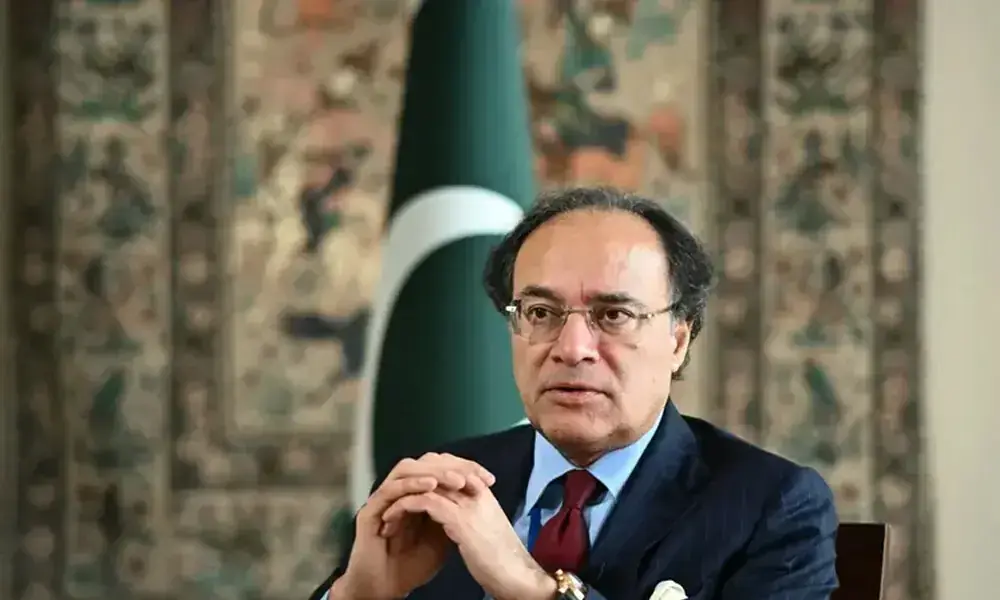
“The finance minister said the government did not view the initial transaction as a one-off exercise and intended to return to the Chinese market for further borrowing.”
That initial capital injection served as the first tranche of an authorized 7.2 billion yuan broader macroeconomic issuance program. To mitigate risk and attract institutional buyers, the transaction was anchored by partial credit guarantees structured jointly by the Asian Development Bank (ADB) and the Asian Infrastructure Investment Bank (AIIB).
Aurangzeb categorized China as the world’s second-largest and deepest capital market, positioning it as an indispensable liquidity source for Pakistan’s forward-looking fiscal requirements. The “panda bonds” mechanism allows foreign governments and corporate entities to capture capital within China’s rigidly controlled domestic market through debt securities denominated strictly in yuan.
Simultaneously, the Ministry of Finance is actively investigating entry into the Japanese sovereign debt arena. Aurangzeb disclosed a direct interest in unlocking Japan’s capital market through the issuance of “samurai bonds”.
“The proposed expansion into Asian bond markets comes as Pakistan seeks to broaden its financing options following a period of economic instability.”
These specialized debt instruments are issued in Tokyo by foreign governments, international institutions, or corporate entities, and they operate strictly under established Japanese financial regulations.
Despite the clear strategic intent, the finance minister cautioned that the Japanese transaction remains in the preliminary evaluation phase. Aurangzeb indicated that the sovereign had not finalized the Japanese transaction and must execute extensive preparatory groundwork and regulatory compliance before officially approaching Tokyo’s institutional investors.
Read More: Pakistan To Refinance Short-Term External Debt Into Longer Maturities To Mitigate Rollover Risks