
Pakistan is strategically restructuring its external liabilities, planning to convert a portion of its short-term debt into longer-maturity instruments over the next two to three years to alleviate persistent rollover risks while capping total external debt near $100 billion.
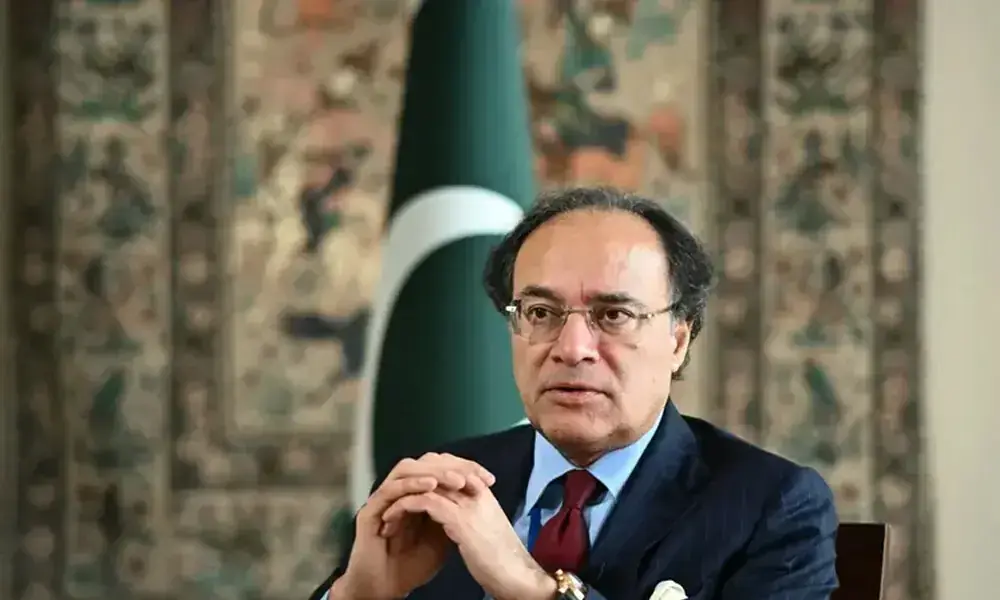
Federal Minister for Finance and Revenue Muhammad Aurangzeb outlined the sovereign debt strategy during an appearance on Bloomberg: The China Show, confirming that the government is pivoting away from emergency external gap filling toward long-term maturity diversification.
“The way I was explaining to you earlier as well, this year, it is not a question that we absolutely need to cover the external financing gap, but for the next two to three years, what we do want to do is to see if some of our short-term external debt can be refinanced into longer tenors, longer maturities, so [the] country does not have to go into this rollover risk of short-term debt.”
Aurangzeb clarified that the overarching objective is not to reduce the total debt volume but to manage the repayment schedule more effectively to prevent continuous liquidity pressure on the national exchequer.
“We want to keep the overall quantum of our external debt, which is close to $100 billion, but think about it mostly as replacement rates, as diversification and elongating maturities,” Aurangzeb stated.
Regarding international capital markets, the finance minister indicated that Islamabad is “not in a rush” to issue standard sovereign bonds within the current fiscal year.
Instead, the Ministry of Finance has issued mandates for alternative financing structures, including “Islamic Sukuks” and novel “dollar-settled but rupee-denominated bonds.” According to the minister, these structured offerings are already generating substantial reverse inquiries from global investors.
“Going forward, we are going to issue RFPs for the remaining Panda bonds. For the first time, you are also going to see if we can go for tokenisation of our existing Eurobonds.”
Beyond debt management, the administration is targeting an economic growth rate exceeding 4% for the fiscal year. This recovery trajectory is expected to be bolstered by aggressive government plans to generate more than $1 billion through the privatization of key state-owned enterprises.
These policy declarations align with Pakistan’s broader diplomatic and financial engagements at the World Bank Group–International Monetary Fund (IMF) Annual Meetings 2026. Aurangzeb traveled to Bangkok, Thailand, last week to lead the official Pakistani delegation for the summit, which runs from October 12 to 18, 2026.
His itinerary features more than 60 scheduled high-level engagements with international financial institutions, development partners, commercial banks, and global credit rating agencies.
The extensive schedule in Bangkok marks a definitive shift in Pakistan’s economic narrative, signaling to global markets that the nation is transitioning from strict macroeconomic stabilization policies toward a sustainable, investment- and export-led growth model anchored by structural reforms.
Read More: Pakistan Takes Charge Of Global Borrowers’ Council At IMF–World Bank Meetings