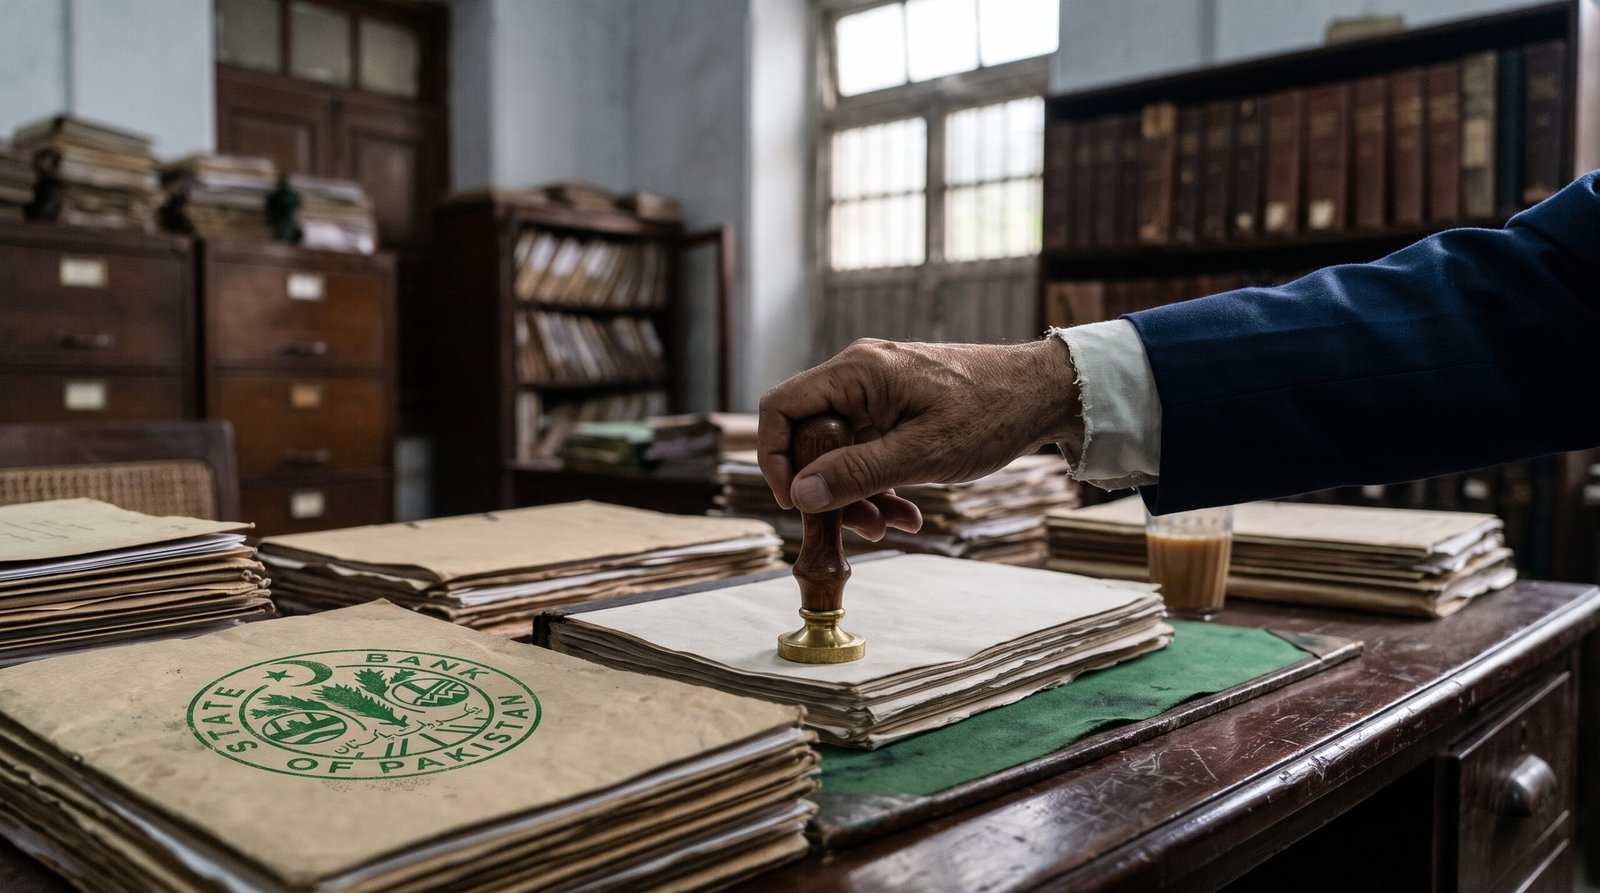
The State Bank of Pakistan (SBP) has comprehensively overhauled the entry barriers to the nation’s financial sector, issuing a consolidated regulatory framework that imposes stringent capital minimums up to Rs 20 billion and completely bars political figures from establishing regulated financial institutions.
Promulgated through “BPRD Circular No. 03” on October 28, 2026, the central bank’s exhaustive licensing and authorization handbook harmonizes previously fragmented instructions. The framework now governs the establishment of conventional and Islamic commercial banks, digital banks, microfinance banks, exchange companies, electronic money institutions (EMIs), payment service providers, and private credit bureaus.
The regulatory architecture, executed under “Section 4C(h)” of the “State Bank of Pakistan Act, 1956”, mandates that all prospective financial entities demonstrate robust financial strength, transparent ownership structures, and highly viable business plans.
“The framework consolidates licensing procedures, eligibility criteria, capital requirements, governance standards and documentation requirements for institutions seeking to enter Pakistan’s financial sector.”
To insulate the banking sector from illicit financial flows and governance vulnerabilities, the SBP has explicitly outlawed the granting of licenses to “shell companies” or “shell banks.” Prospective sponsors, beneficial owners, directors, and chief executives are subjected to rigorous “fit-and-proper criteria”.
The disqualification parameters are severe. The central bank categorically bars members or office-bearers of political parties, elected legislators, and active public office holders from obtaining a license or operating as sponsor shareholders. Furthermore, individuals with prior criminal convictions, declared bankruptcies, or historical associations with institutions that suffered regulatory license revocations are permanently disqualified.
Also Read: Federal Constitutional Court Rejects Income Support Levy Appeals, Citing Constitutional Violations
Capital Formatting And Application Timelines
Under the consolidated regime, complete applications meeting all prescribed regulatory requirements will face a general processing timeline of six to eight weeks. However, this operational window remains contingent upon external feedback, applicant responsiveness, and secondary regulatory clearances.
The SBP has maintained a strict moratorium on the establishment of new commercial banks wholly owned by local sponsors. Foreign investors, conversely, retain the right to establish banks independently or through strategic partnerships with local capital, subject to targeted regulatory conditions. The central bank also retained the mandatory requirement for commercial banks to secure a public listing on the Pakistan Stock Exchange (PSX), granting a maximum grace period of four years from the commencement of business.
The regulatory framework establishes precise, tiered capital requirements and non-refundable application processing fees designed to ensure only heavily capitalized entities enter the market.
| Financial Institution Category | Minimum Capital Requirement | Non-Refundable Processing Fee |
| Locally Incorporated Commercial Banks | Rs 20 billion | Rs 5 million |
| Foreign Bank Branches (1 to 5 branches) | Rs 5 billion | Rs 5 million |
| Foreign Bank Branches (6 to 50 branches) | Rs 10 billion | Rs 5 million |
| Digital Retail Banks (Third Year Target) | Rs 4 billion | Rs 5 million |
| Digital Full Banks (Progression Target) | Rs 10 billion | Rs 5 million |
| Microfinance Banks & Exchange Companies | Variable by tier | Rs 2 million |
| EMIs, PSOs, PSPs & Credit Bureaus | Variable by tier | Rs 200,000 |
For the rapidly expanding digital banking sector, the SBP has segmented licensing into distinct operational phases. “Digital retail banks” must secure a baseline capital of Rs 1.5 billion during the restricted licensing stage, scaling to Rs 2 billion at commercial launch, and ultimately achieving Rs 4 billion by the third financial year of operations. “Digital full banks” face an aggressive capitalization trajectory, requiring Rs 6.5 billion at initial licensing, subsequently expanding to Rs 8 billion and capping at Rs 10 billion during the operational progression period.
“Applicants must also demonstrate their ability to comply with anti-money laundering, counter-terrorism financing, consumer protection, data security and other applicable regulatory requirements.”
The overarching corporate governance requirements mandate specific board compositions, the inclusion of independent directors, and strict limitations on family representation within senior management. The SBP retains unilateral authority to revoke any approval or license secured through misrepresentation or the submission of false data, though rejected applicants retain the right to formally appeal the central bank’s decision.