ISLAMABAD: The Federal Board of Revenue (FBR) has made electronic production monitoring mandatory for manufacturers of synthetic leather, paper, and paperboard, setting strict deadlines for factories to install automated tracking systems aimed at curbing tax evasion and halting the removal of unmonitored goods.
Issued under Section 40C of the Sales Tax Act, 1990, and relevant provisions of the Sales Tax Rules, 2006, Sales Tax General Order (STGO) No. 38 and STGO No. 39 of 2026 take immediate effect. Synthetic and artificial leather manufacturers have been directed to install and operationalise the prescribed equipment by November 30, while paper and paperboard producers must comply by December 15.
Synthetic Leather: AI Cameras, Sensors, and Strict Tolerances
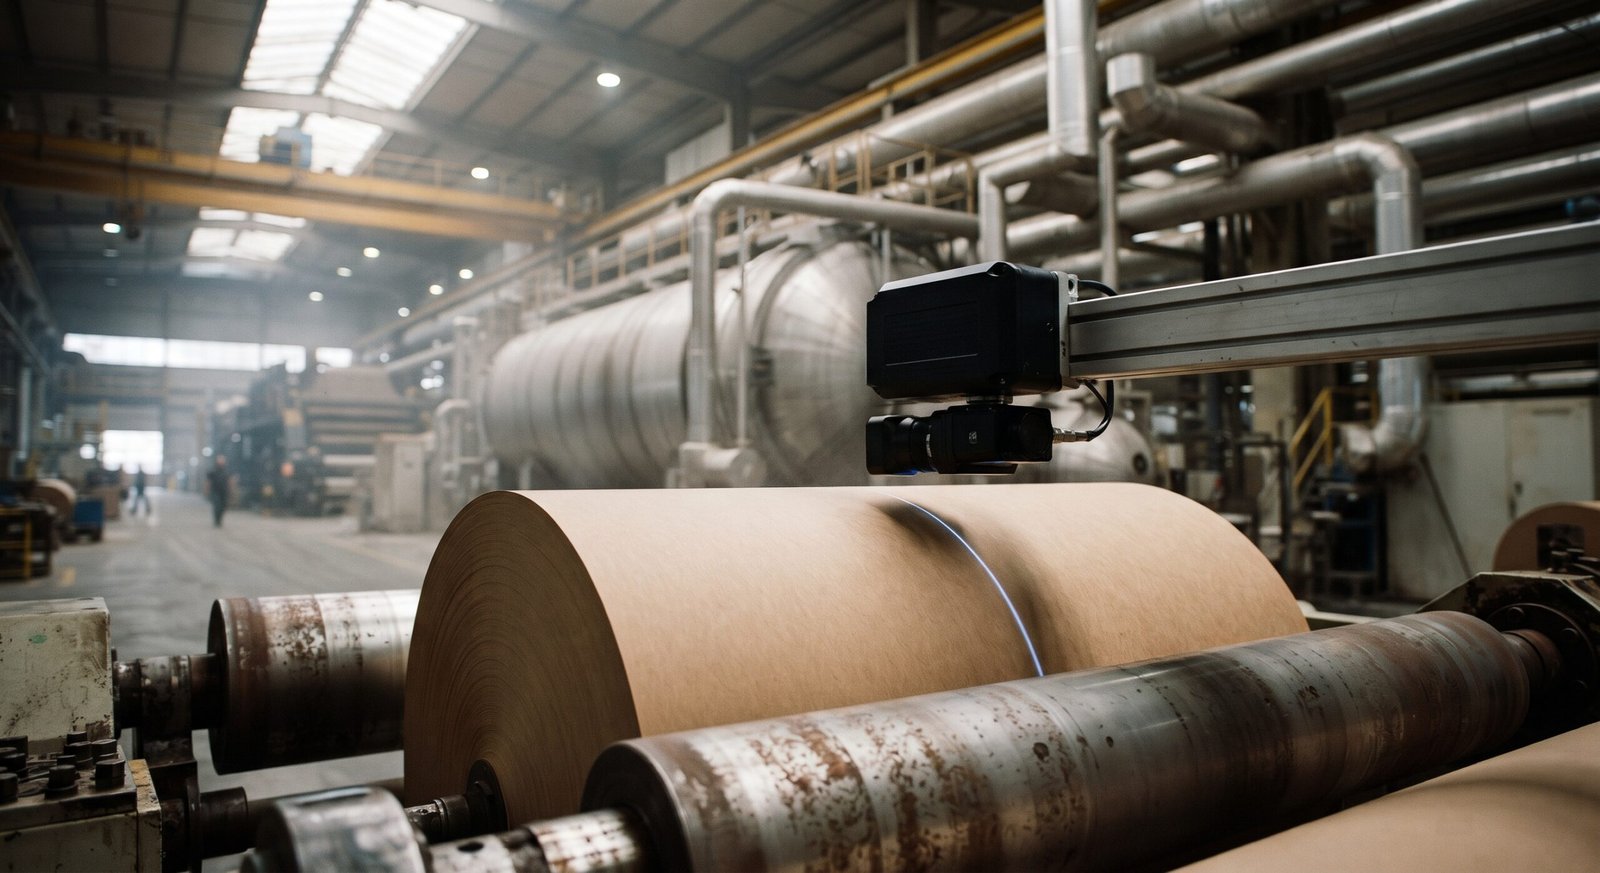
Under the directive governing the synthetic leather industry, manufacturers involved in coating, laminating, finishing, winding, rewinding, inspecting, and cutting—including contract manufacturers and composite facilities—must install sensor-based production measurement systems paired with AI-enabled industrial cameras at every active roll-producing line. The FBR has designated the National Radio and Telecommunication Corporation (NRTC) as the authorised vendor for the sector.
The automated system must measure the running length of synthetic leather at a 0.1-metre resolution, identify each finished roll, and log length, production time, roll count, and video evidence. Key technical mandates include:
- Camera Specifications: Industrial cameras with a minimum 4-megapixel resolution recording at 25 frames per second. Every roll-cutting event must generate a time-stamped snapshot alongside video footage covering at least 10 seconds before and after the cut.
- Accuracy and Alerts: Systems must maintain at least 99 per cent measurement and roll-count accuracy (with a minimum acceptable floor of 95 per cent) and 99 per cent daily uptime. Any discrepancy exceeding 0.5 per cent between individual roll records and cumulative output will automatically trigger an alert.
- Data Retention and Transmission: Production data must stream securely to the FBR’s Central Control Unit. Manufacturers are required to retain video footage for at least 30 days and production logs, snapshots, and system records for at least 90 days.
Any equipment failure, damage, or suspected tampering must be reported within one hour. Beyond real-time output tracking, tax officials are empowered to reconcile electronic production logs against sales tax returns, invoices, inventory stocks, electricity consumption, and purchases or imports of key raw materials—including PVC and polyurethane resins, plasticisers, and base fabric.
Paper and Paperboard: GSM Tracking and Major Mills Named
Separately, STGO No. 39 requires registered paper and paperboard manufacturers—including composite units, though excluding businesses engaged solely in cutting and printing—to install electronic systems capable of detecting, weighing, and counting output by grade and grammage, measured in grams per square metre (GSM). Where mills divert their own paper or paperboard for in-house manufacturing of other products on the same premises, the internal diversion point must also be electronically monitored.
The FBR has authorised ISSM Labelling Solutions (Pvt) Ltd as the approved vendor for the paper and paperboard sector, directing mills to complete hardware, software, and connectivity installations on every paper machine and line by December 15. The order lists 45 registered manufacturers across tax jurisdictions—including Century Paper and Board Mills, Bulleh Shah Packaging, Security Papers, Nishat Packaging, Tetra Pak Pakistan, and Cherat Packaging—while clarifying that the mandate applies equally to all eligible manufacturers omitted from the non-exhaustive annex.
The tax authority also noted that these requirements operate in addition to STGO No. 27 of 2026, issued on October 7, meaning previously installed video surveillance systems at paper mills must remain operational.
Compliance Costs and Enforcement
Under both orders, manufacturers are strictly prohibited from removing or supplying finished rolls or goods from factory premises unless their production has been electronically monitored and logged. Factory owners must bear the costs of physical infrastructure, electricity, internet connectivity, installation access, and prescribed vendor charges.
Chief Commissioners Inland Revenue have been instructed to identify all covered manufacturing units, nominate focal persons, coordinate with authorised vendors, and enforce timely rollouts within their jurisdictions. Violations—including equipment tampering, concealment of active production lines, or the removal of unmonitored goods—will trigger enforcement action under the Sales Tax Act and applicable rules.