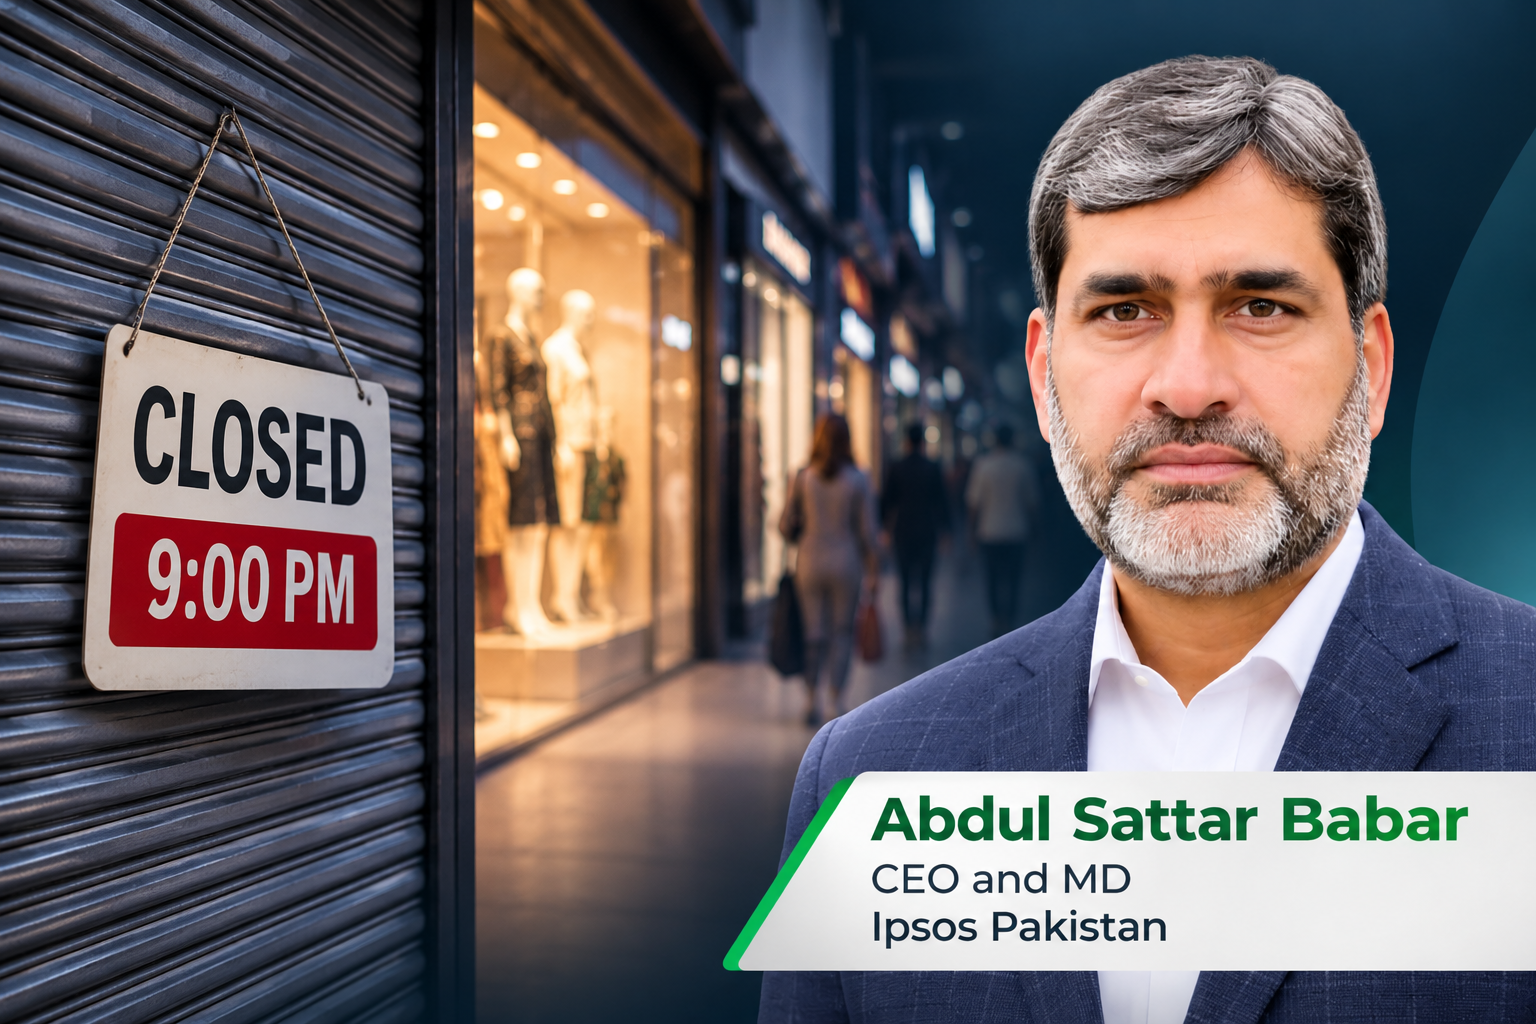
LAHORE, November 17, 2026: Pakistan’s controversial 9pm market-closing policy came under renewed scrutiny on Tuesday as a comprehensive study presented at the 6th Pakistan Future of Retail Business Summit & Expo 2026 revealed a 42 per cent decline in average daily retail transactions, shrinking profitability, reduced shopping activity among women and growing concerns about employment across the country’s retail sector.
Presenting the findings at the Pearl-Continental Hotel in Lahore, Abdul Sattar Babar, Chief Executive Officer of Ipsos Pakistan, highlighted the economic and social implications of restricting commercial operating hours, raising fundamental questions about whether the government’s energy-conservation strategy is delivering sufficient benefits to justify its impact on businesses and consumers.
The presentation, titled The Impact of Early Closing Time Regulations on Pakistan’s Retail Sector, formed part of the sixth edition of the Pakistan Future of Retail Business Summit & Expo, organised by the Chainstore Association of Pakistan (CAP) in collaboration with TerraBiz under the theme Retail, Rebuilt.
The Scoop served as the Official Media Partner of the conference, which brought together leading retailers, industry executives, business associations, policymakers and other stakeholders to examine the challenges and opportunities confronting Pakistan’s retail economy.
The Ipsos research, whose initial findings were publicly released earlier this month, involved 1,046 consumers, 300 retailers across 53 malls and markets, and 25 key informants from trade bodies, manufacturing companies, retail brands and government institutions.
It also included international benchmarking covering 15 countries, including Pakistan, using 81 reference sources, among them 44 government or legal instruments.
Although the study does not establish that early market closures alone caused the observed deterioration, its findings indicate that restricted operating hours are adding pressure to a sector already struggling with difficult economic conditions.
Retail Transactions Decline as Businesses Lose Valuable Trading Hours
One of the most striking findings presented by Babar was the contraction in daily retail transactions.
According to Ipsos, average transactions per shop declined from 86 before the restrictions to 50 afterwards, representing a reduction of approximately 42 per cent.
The study also found that average daily operating hours decreased from 11.2 to 9.6, eliminating approximately 1.6 hours of trading time.
For many retailers, the lost hours are particularly important because they coincide with the period when working consumers traditionally visit markets and shopping centres.
The proportion of retailers reporting high customer traffic between 4pm and 8pm declined from 63 per cent to 32 per cent.
Meanwhile, the share identifying the period after 8pm as their strongest sales window dropped from 44 per cent to just 8 per cent.
An executive from the footwear and apparel industry interviewed during the research estimated that approximately 40 to 50 per cent of daily customer footfall traditionally occurred between 7pm and 9pm.
The findings challenge the assumption that consumers can simply move their shopping to earlier hours without affecting overall spending patterns.
The decline was also visible across individual product categories.
In electronics accessories, average daily transactions declined from 80 to 35, while footwear retailers reported a reduction from 85 to 38 transactions.
Clothing retailers experienced a decline from 104 to 60 transactions per day.
Although these figures are based on surveyed businesses rather than audited national transaction records, they illustrate the scale of the reported commercial deterioration.
Profitability Takes a Hit as Operating Costs Remain
The research paints an equally concerning picture of retailer profitability.
Before the regulations, 79 per cent of surveyed retailers described their overall sales performance as good.
That proportion subsequently declined to 34 per cent.
Similarly, the share reporting high daily sales fell from 62 per cent to 19 per cent, while those reporting high customer spending declined from 56 per cent to 13 per cent.
Perhaps more significantly, retailers describing their profitability as high declined from 67 per cent to 26 per cent.
These figures measure retailers’ assessments rather than audited profit margins. However, the deterioration across several indicators suggests that businesses are facing considerable pressure.
Retailers interviewed during the study argued that shorter operating hours do not necessarily produce equivalent reductions in their expenses.
Commercial rents, employee salaries, inventory costs and numerous other operating expenses continue regardless of whether a shop closes earlier.
Electricity consumption may decline when stores operate for fewer hours, but the associated financial savings do not automatically compensate for lost transactions and weaker customer spending.
This creates a particular challenge for organised retailers operating from expensive commercial locations, including shopping malls and high-street outlets.
Women’s Shopping Activity Declines Disproportionately
Beyond the commercial consequences, the research revealed a significant change in consumer shopping behaviour, particularly among women.
According to Ipsos, the average number of monthly shopping trips among women declined from 7.2 to 5.8, representing a reduction of approximately 19 per cent.
Among men, the decline was considerably smaller, with average monthly shopping trips falling from 10.7 to 10.4, or approximately 3 per cent.
Across the entire consumer sample, shopping frequency declined from 9.4 trips per month to 8.7.
The difference between male and female shopping patterns raises questions about whether restricted market timings disproportionately affect particular consumer groups.
The research did not establish the precise reasons behind the gender disparity.
However, factors such as office hours, family responsibilities, transportation arrangements and the availability of time for shopping may influence consumer decisions.
The findings are particularly important in a country where family shopping frequently takes place after working hours.
Indeed, 53 per cent of consumers surveyed said finding time for shopping had become more difficult following the introduction of early closing regulations.
Only 15 per cent reported that shopping had become easier, while 32 per cent experienced no change.
Family Shopping and Leisure Activity Are Declining
The impact appears to extend beyond ordinary retail purchases.
According to the Ipsos research, the proportion of consumers who rarely or never shop with their families increased from 62 per cent before the restrictions to 71 per cent afterwards.
At the same time, the proportion of consumers frequently shopping with their families declined from 19 per cent to 13 per cent.
Leisure shopping experienced an even sharper deterioration.
Before the policy changes, 74 per cent of consumers said they rarely or never shopped for leisure.
That proportion increased to 87 per cent.
The share frequently engaging in leisure shopping declined from 13 per cent to just 5 per cent.
These findings carry potentially significant implications for Pakistan’s shopping malls and organised retail destinations.
Modern shopping centres increasingly depend on consumers visiting not merely to purchase specific products, but also to spend time with friends and families, explore new brands and participate in recreational activities.
Reduced leisure footfall can therefore affect a wider commercial ecosystem, including fashion retailers, entertainment businesses, food outlets and other services located within shopping destinations.
The study does not quantify the resulting financial losses across these businesses, but the decline in leisure-oriented visits suggests that the implications of closing-time regulations extend beyond individual retail outlets.
Shoppers Shift Towards Neighbourhood Stores
The research further indicates that consumers are changing where they prefer to shop.
Neighbourhood shops increased their share as the most frequently used shopping format from 27 per cent to 31 per cent.
Shopping malls, by contrast, declined from 8 per cent to 6 per cent, while traditional bazaars and markets fell from 36 per cent to 34 per cent.
These figures represent reported consumer shopping preferences rather than audited sales market shares.
Nevertheless, the trend suggests that convenience and proximity may be becoming more important as consumers adapt to shorter retail operating hours.
For shopping malls and larger retail destinations, the shift could create further challenges in attracting customers who must balance shopping with work and family commitments.
The implications may also extend to investors considering new retail developments, particularly projects that depend on sustained evening footfall.
Retail Employment Comes Under Pressure
Another important finding concerned employment.
According to the survey, 12 per cent of retailers reported reducing staff as businesses adjusted to changing commercial conditions.
Meanwhile, 73 per cent said they had started opening earlier in the day, while 34 per cent reported introducing or expanding online sales.
These adjustments indicate that retailers are attempting to recover lost trading opportunities and reduce operational pressure.
However, the shift towards earlier opening does not guarantee the recovery of evening customers, particularly those who cannot leave work before conventional business hours.
Similarly, expanding e-commerce does not necessarily replace purchases that would otherwise have occurred in physical stores.
Industry executives interviewed by Ipsos questioned the assumption that consumers who cannot visit a shop will automatically make the same purchase online.
The research does not establish the total number of jobs lost nationally, nor does it isolate how many staffing decisions were caused exclusively by the timing restrictions.
Nevertheless, the finding that some retailers have already reduced employment highlights the need for further assessment of the policy’s workforce implications.
Punjab and Islamabad Face Sharper Commercial Pressures
One of the study’s most important analytical findings came from comparing businesses operating in restricted and unrestricted areas during the survey period.
The research classified Punjab, Islamabad Capital Territory and Balochistan as restricted areas, while Sindh and Khyber Pakhtunkhwa were categorised as unrestricted following the lifting of earlier restrictions in May 2026.
The sample included 179 retailers in restricted areas and 121 in unrestricted areas.
According to the findings, the proportion of retailers rating overall sales as good declined from 82 per cent to 28 per cent in restricted markets.
In unrestricted markets, the corresponding decline was from 74 per cent to 42 per cent.
A similar pattern emerged in profitability assessments.
In restricted areas, the proportion describing profitability as good fell from 67 per cent to 22 per cent.
In unrestricted markets, the corresponding figure declined from 68 per cent to 32 per cent.
Evening customer footfall also deteriorated more sharply in restricted areas.
The proportion reporting high evening traffic declined from 56 per cent to 20 per cent, compared with a reduction from 73 per cent to 50 per cent in unrestricted markets.
These comparisons suggest that early closing regulations may be imposing additional pressure on businesses beyond the challenges arising from the broader economy.
However, economic conditions deteriorated in both groups.
Differences in local markets, business categories, purchasing power and other factors could also influence the results.
The findings therefore provide evidence of an association between restrictions and weaker trading outcomes, rather than a definitive measurement of the policy’s independent causal effect.
Are Pakistan’s Energy Savings Actually Being Measured?
Perhaps the most consequential question emerging from the presentation concerns the government’s original justification for compulsory early market closures.
Pakistan introduced and subsequently revised market-closing restrictions in 2026 as part of measures to conserve energy and fuel amid international supply disruptions and price pressures.
On September 17, the federal government announced renewed austerity measures and continued the 9pm market-closing requirement, while asking provincial and regional governments to consider similar conservation measures.
Energy security remains a legitimate national concern.
However, the Ipsos findings raise questions about how the economic costs of the restrictions are being weighed against the benefits.
According to the survey, 56 per cent of retailers believed the policy had achieved its energy-conservation objective.
Yet only 41 per cent reported a reduction in their own electricity bills.
The distinction is important: individual electricity bills do not establish how much electricity has been saved nationally, especially when tariffs, fixed charges and consumption patterns also influence the amount payable.
The presentation highlighted the absence of a published national figure directly comparing the electricity saved through early market closures with the economic activity potentially lost.
Without such information, policymakers face difficulty determining whether the current approach is the most efficient available.
A comprehensive assessment would require verified data on electricity consumption, peak demand, fuel savings, retail sales, business profitability and employment.
Bangladesh Emerges as Pakistan’s Only Comparable Country
The international comparison presented by Ipsos offers another important perspective.
Of the 14 countries examined alongside Pakistan, Bangladesh was the only one identified as using early shop closures specifically for energy conservation.
Bangladesh’s approach also involved repeated regulatory changes, with seven adjustments to closing-hour arrangements recorded between April and October 2026.
The study found that other economies generally regulate retail hours for different reasons.
France and Germany have labour protections affecting certain working hours, while the United Kingdom imposes restrictions on Sunday trading by large stores in England and Wales.
Indonesia applies operating-hour regulations to particular large retail formats, partly to protect traditional shops.
Other markets, including the United Arab Emirates and Hong Kong, were not found to have comparable general early-closing requirements in the sources reviewed.
The findings suggest that Pakistan’s reliance on compulsory early retail closures for energy conservation is unusual among the countries examined.
Other Countries Offer Alternatives to Early Closures
The international research also highlighted several ways governments and businesses have reduced electricity demand without relying primarily on compulsory early shop closures.
In France, an energy-saving initiative involving approximately 53,000 shops and shopping centres achieved a reported 15 per cent reduction in electricity consumption over three years through measures such as improved lighting, heating and refrigeration management.
Brazil’s historical electricity-rationing programme during the 2001–2002 energy crisis achieved consumption reductions of approximately 20 per cent or more using consumption quotas, incentives and penalties.
The Philippines has used an Interruptible Load Programme involving major electricity consumers, allowing participating businesses to reduce their demand on the public grid during shortages.
Indonesia has employed differentiated electricity tariffs for certain large commercial consumers during peak demand periods.
Dubai has pursued efficiency programmes involving cooling systems, building improvements and targeted electricity management, with the study citing approximately 2.2 terawatt-hours of savings over the 2012–2021 period.
These examples involve different economies, regulatory systems and energy-market conditions, so their results cannot be directly applied to Pakistan.
Nevertheless, they demonstrate that governments have alternatives to limiting commercial activity when designing energy-conservation policies.
Half of Retailers Oppose Early Closing
The study also examined retailers’ attitudes towards the restrictions.
According to Ipsos, 50 per cent of surveyed retailers opposed early closing, compared with 32 per cent who supported it.
Another 18 per cent neither supported nor opposed the policy.
Among business owners, opposition increased to 54 per cent.
Interestingly, even retailers who believed the policy was producing energy savings frequently wanted the regulations changed.
Among 169 respondents who perceived the energy-conservation objective as having been achieved, approximately 57 per cent wanted revised closing hours, while another 21 per cent favoured removing the restrictions altogether.
Only around one-fifth supported retaining the existing timings.
The findings suggest that support for conserving electricity does not necessarily translate into support for the particular method adopted by the government.
Traders Complain of Inadequate Consultation
The presentation also examined the government’s engagement with affected businesses.
Of the 25 key informants interviewed, 10 raised concerns about the absence of adequate consultation with traders before decisions were taken.
Another 10 identified uneven or heavy-handed enforcement, while five highlighted sudden or unstable regulatory changes.
A senior executive from a national apparel retail chain explained that adjusting to new operating hours could require four to six weeks, with repeated changes disrupting the adjustment process.
For businesses, uncertainty over closing times affects far more than daily sales.
It can influence employee schedules, deliveries, inventory management, marketing campaigns and future investment decisions.
Industry representatives argued that policymakers should consult retailers before introducing major changes and provide sufficient notice for businesses to adjust.
A Policy Debate That Goes Beyond Retailers
The findings presented at the summit raise broader questions about Pakistan’s approach to economic management.
The retail sector supports employment, commercial property markets, distribution networks, manufacturing demand and consumer services.
When retail transactions weaken, the impact can extend beyond shopkeepers to manufacturers, suppliers, transport operators and employees working across the commercial supply chain.
However, the scale of these broader effects requires further independent measurement.
Similarly, the country’s energy-conservation challenges cannot be dismissed.
Pakistan remains exposed to international fuel prices, supply disruptions and the financial pressures associated with its electricity system.
The real policy challenge is therefore to establish whether compulsory early market closures deliver measurable benefits that outweigh their economic consequences, or whether more targeted conservation measures could achieve comparable results with less disruption.
What Ipsos Recommends
The presentation concluded with recommendations centred on transparency, consultation and alternative approaches to energy conservation.
It called for government authorities to communicate the measurable gains and losses associated with the policy, engage retailers when determining operating hours and examine international examples of consumption management.
The research also emphasised the importance of recognising Pakistan’s evening shopping patterns, particularly the commercial significance of the 7pm to 9pm period.
For policymakers, the immediate task is to move beyond general assumptions about electricity savings and establish a transparent framework for evaluating commercial restrictions.
That would involve comparing energy savings with the impact on transactions, profitability, customer behaviour and employment.
The findings presented by Abdul Sattar Babar at the Future of Retail Summit ultimately raise a question that Pakistan’s economic policymakers can no longer afford to overlook: if the country is losing trading hours, customer transactions and commercial opportunities in the name of conserving energy, how much electricity is actually being saved — and is the trade-off economically justified?