
KARACHI: ABHI Microfinance Bank (ABHI MFB) is heading into its highly anticipated Initial Public Offering (IPO) on the back of one of the most dramatic institutional turnarounds in Pakistan’s recent banking history. After navigating severe financial headwinds, the bank—formerly known as FINCA Microfinance Bank—has aggressively pivoted back to profitability under its new ownership, driven by an explosion in core earning power and a massive expansion in secured lending.
The sheer scale of the recovery is detailed in the bank’s latest financial disclosures. After posting crippling net losses of PKR 1.73 billion in calendar year 2023 and PKR 1.75 billion in CY24, the institution arrested the slide in CY25, its first full year under ABHI’s ownership, posting a net profit of PKR 1.02 billion. The momentum has only accelerated in the current year. For the first half of CY26 (1H CY26), ABHI MFB reported a record net profit of PKR 1.50 billion, meaning the bank has already eclipsed its entire full-year CY25 profit in just six months. Looking ahead, the IPO prospectus forecasts aggressive continued growth, projecting net profit after tax to scale to PKR 2.93 billion by the end of CY26, PKR 4.13 billion in CY27, and PKR 5.44 billion by CY28.
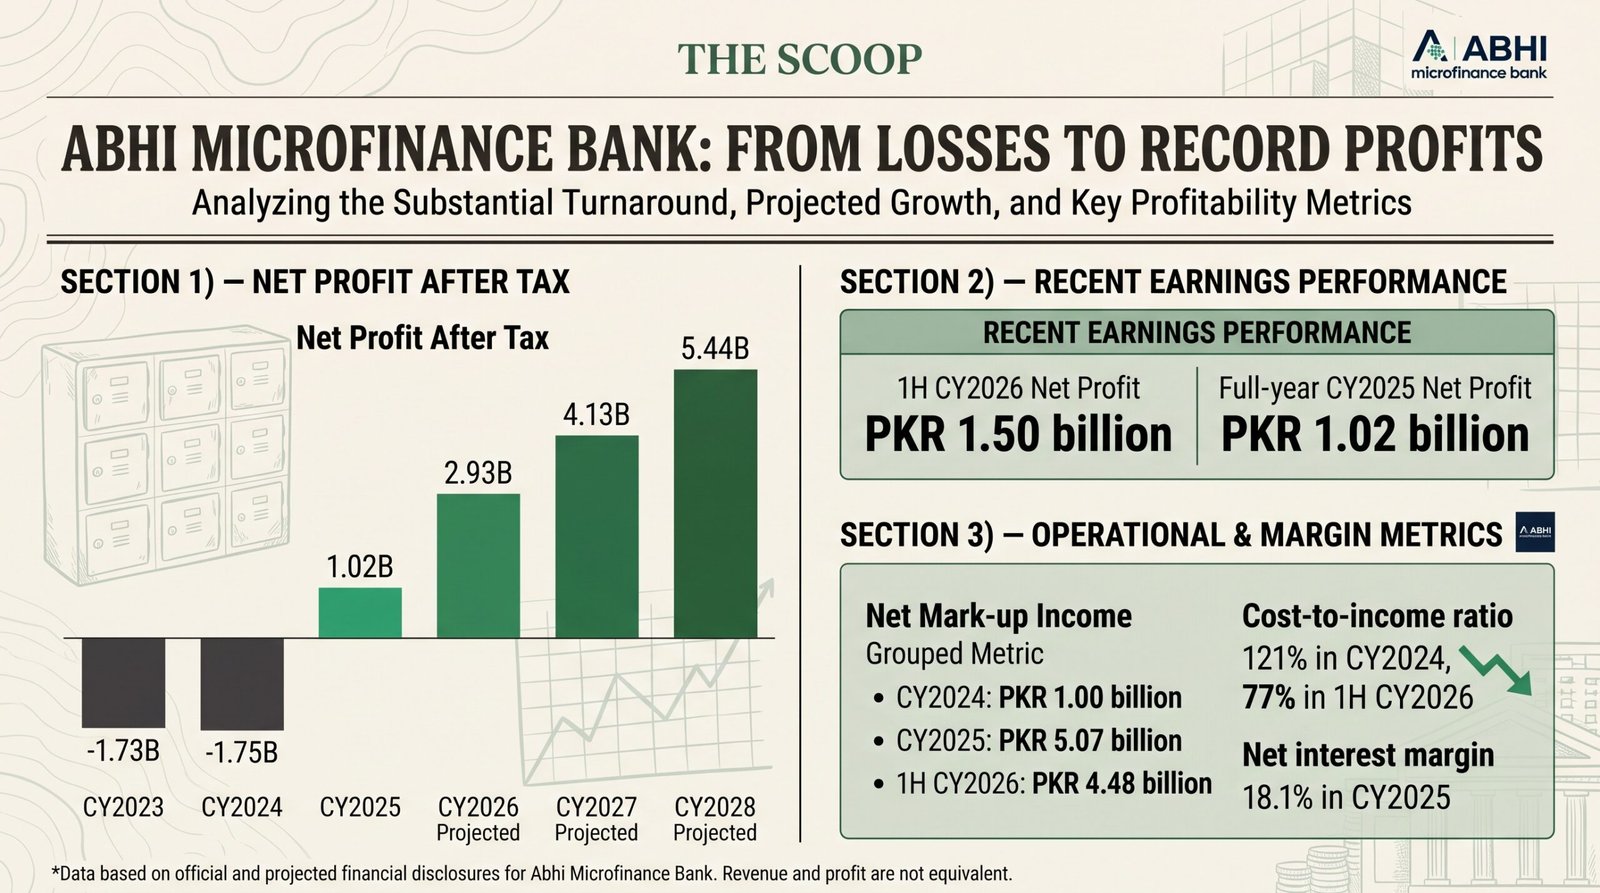
This profitability is underpinned by a fivefold surge in core earning power and stringent operational cost controls. Net mark-up income skyrocketed from just PKR 1.00 billion in CY24 to an impressive PKR 5.07 billion in CY25. This aggressive trajectory carried into 1H CY26, with net mark-up income hitting PKR 4.48 billion in just six months. Operational efficiency has followed suit, with the bank’s cost-to-income ratio plummeting from a bloated 121% in CY24 down to a lean 77% by 1H CY26. The bank closed CY25 with an exceptional net interest margin of 18.1%.
Also Read: Pakistan’s Development Divide Exposed As Welfare Index Reveals Stark District Inequalities
The primary driver behind this income surge is the rapid and highly secured scaling of the bank’s lending operations. In just 18 months, ABHI MFB expanded its loan book by 2.7 times. Net advances grew from PKR 18.4 billion in December 2024 to PKR 37.6 billion in December 2025, reaching PKR 49.5 billion by June 2026. Despite this rapid credit expansion, the bank has successfully insulated itself against systemic default risks. Its Non-Performing Loan (NPL) ratio stood at an exceptionally low 0.68% in CY25, sitting well below the industry average. This pristine asset quality is secured by a highly risk-averse lending model where approximately 90% of the bank’s advances are fully gold-backed. While this concentration exposes the bank to swings in global gold prices, it has practically eliminated unsecured default risks during its critical turnaround phase.
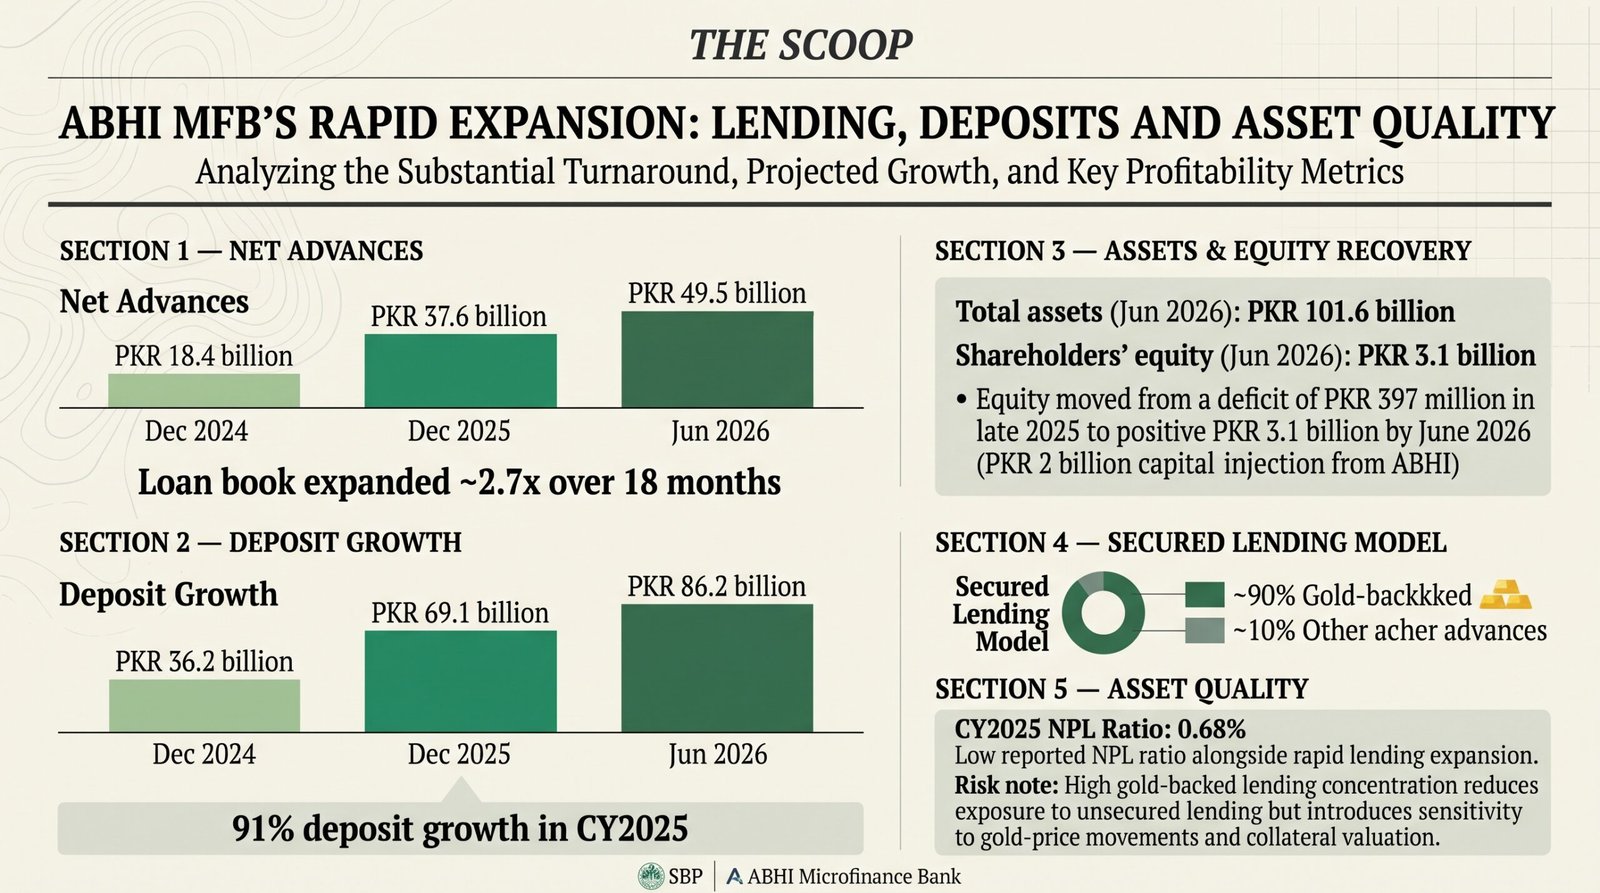
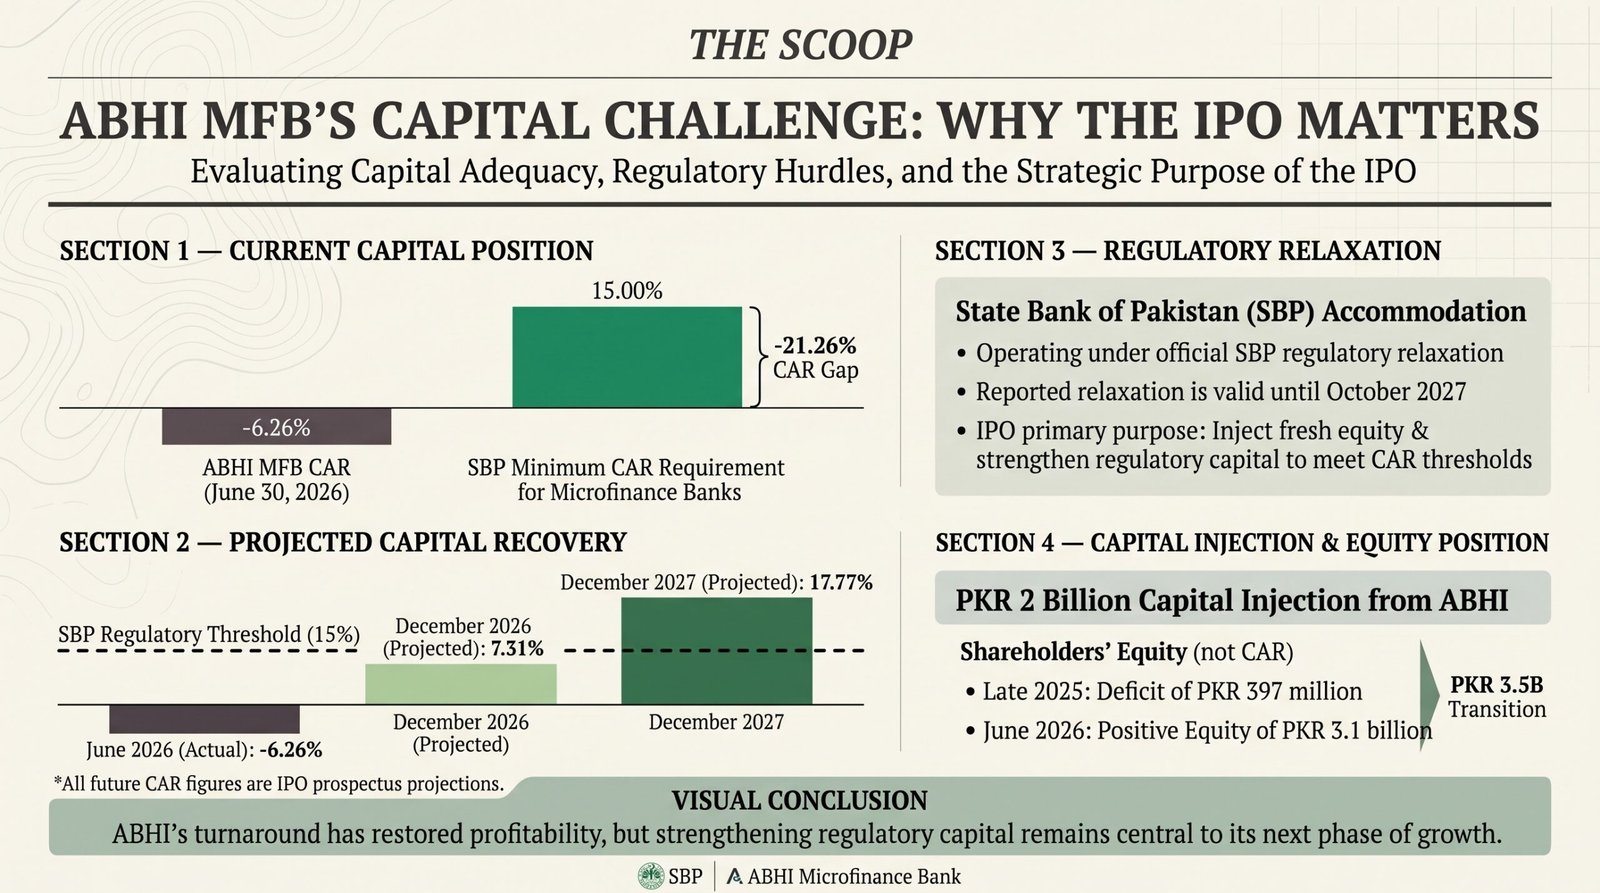
Customer trust and liquidity have scaled in tandem with the bank’s lending portfolio. Total deposits nearly doubled in CY25, registering a 91% growth to reach PKR 69.1 billion, up from PKR 36.2 billion in December 2024. By June 2026, the deposit base had swelled further to PKR 86.2 billion. This influx of capital has pushed the microfinance bank’s total assets past the PKR 101.6 billion mark as of June 2026. This has helped repair the bank’s balance sheet, pushing its equity from a deficit of PKR 397 million in late 2025 to a positive PKR 3.1 billion by mid-2026, aided by a PKR 2 billion capital injection from ABHI itself.
The institution is shifting aggressively toward a digital-first lending model. Utilizing the technological backbone of its parent company, the bank is expanding its portfolio to include Earned Wage Access (EWA), payroll-linked loans, digital merchant finance, and automated credit scoring—allowing it to scale rapidly without relying heavily on traditional brick-and-mortar branch expansion.
However, the rapid turnaround comes with significant regulatory hurdles. The bank’s Capital Adequacy Ratio (CAR) stood at a negative 6.26% as of June 30, 2026, well below the State Bank of Pakistan’s 15% minimum threshold for microfinance banks. The institution currently operates under an SBP regulatory relaxation valid until October 2027. The primary objective of the current IPO is to inject fresh equity directly into the bank to strengthen its regulatory capital base and clear this threshold. The bank projects that the IPO proceeds will lift its CAR to 7.31% by the end of 2026 and comfortably to 17.77% by the end of 2027.
Institutional appetite for the turnaround story has already been proven. In the book-building phase, the offering drew bids for 157.17 million shares against the 99 million offered, leaving the institutional round 1.6 times oversubscribed and establishing an indicative strike price of PKR 15.50 per share against a floor price of PKR 15.00.
To fuel its continued expansion, ABHI MFB has reserved 33 million shares for the general public. Retail investors are invited to participate in the public subscription on November 12 and 13, 2026, at the established strike price of PKR 15.50 per share. The minimum application threshold is set at 500 shares, requiring a highly accessible base investment of PKR 7,750. Investors can subscribe seamlessly through the Central Depository Company’s Centralized e-IPO System (CES), the PSX e-IPO System (PES), or through designated banking channels.