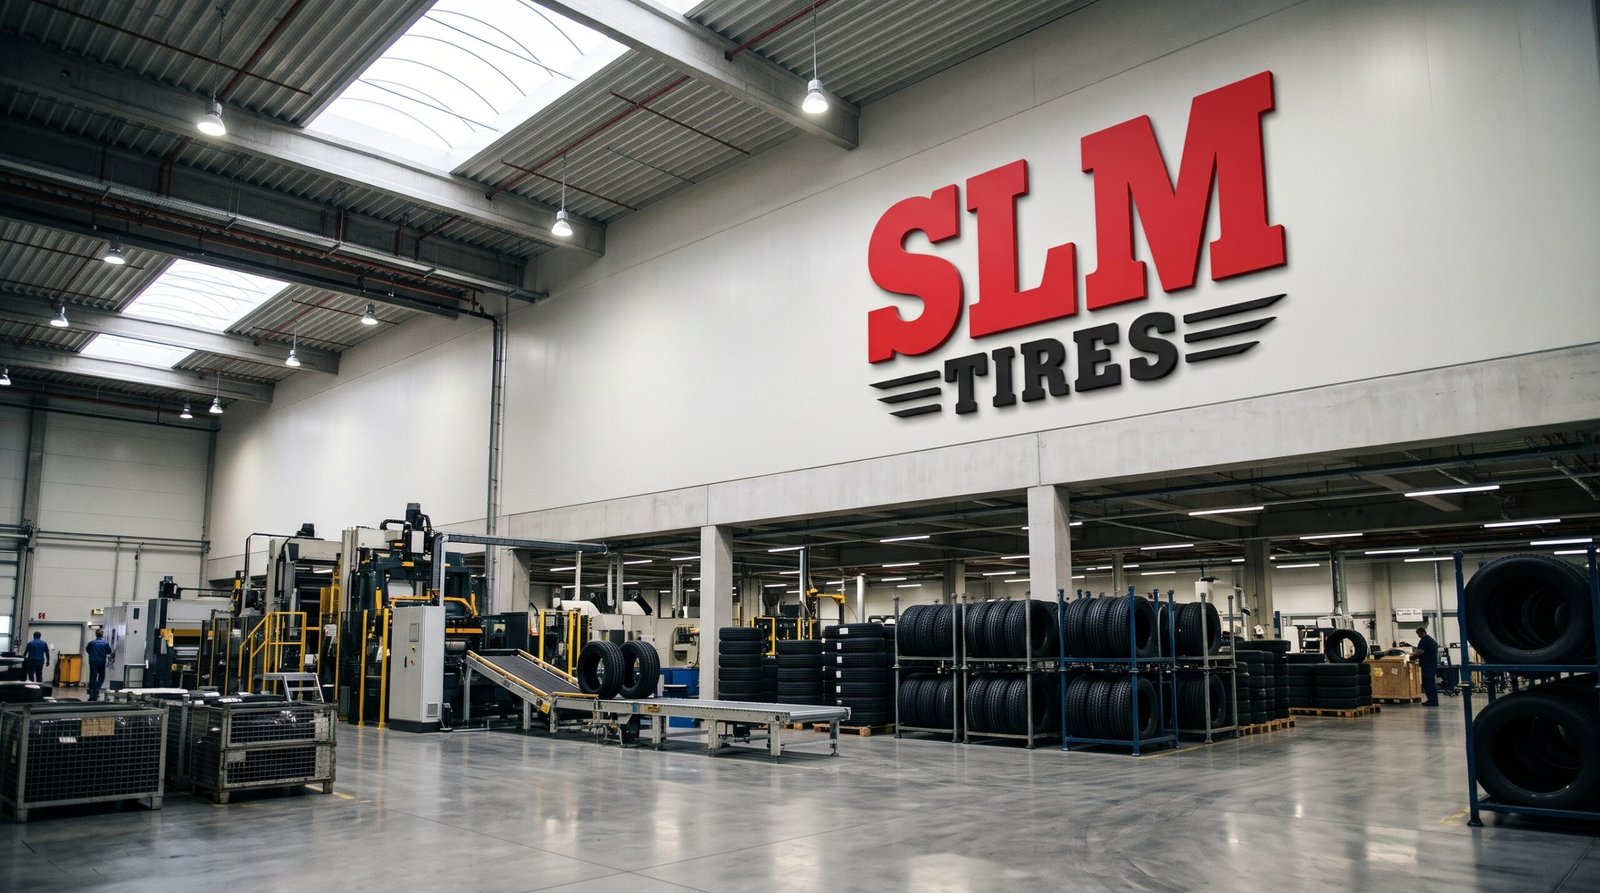
Service Long March Tyres Limited (PSX: SLM) reported a 23.09% year-on-year surge in consolidated profit after taxation, reaching Rs3.69 billion for the quarter ended September 30, 2026. The robust bottom-line expansion, up from Rs3.00 billion in the corresponding period last year, was primarily driven by aggressive top-line sales growth and an exponential spike in secondary income.
Revenue from contracts with customers expanded by 34.29% to reach Rs22.19 billion, a substantial increase from Rs16.53 billion recorded in the same quarter last year. However, macroeconomic inflationary pressures on manufacturing severely constrained the company’s margin growth.
The cost of sales outpaced revenue expansion, rising 36.56% to Rs17.48 billion, compared to Rs12.80 billion in the prior year. This dynamic limited gross profit growth to 26.49%, settling at Rs4.72 billion.
“While top-line sales expanded aggressively, the disproportionate surge in the cost of sales indicates severe underlying pressure on operational margins within the heavy manufacturing sector.”
Operating overheads witnessed aggressive inflation during the quarter. Distribution costs skyrocketed by 77.66% to Rs635.69 million, while administrative expenses jumped 56.81% to Rs331.64 million. Despite these mounting operational pressures, the company managed an 18.68% expansion in operating profit, bringing it to Rs3.75 billion.
The most critical catalyst preventing profit erosion was a massive injection of “other income,” which surged by an astonishing 924.57% to hit Rs289.58 million, up from a mere Rs28.26 million last year.
This secondary capital infusion effectively neutralized escalating borrowing expenses. Finance costs and other charges climbed 60.38% to Rs263.84 million, reflecting tighter domestic credit conditions. Conversely, other expenses declined slightly by 5.74% to Rs171.47 million.
| Financial Metric (Quarter Ended Sept 30) | 2026 (Rs. 000) | 2025 (Rs. 000) | YoY Change |
| Revenue from Contracts | 22,194,907 | 16,527,956 |
34.29%
|
| Cost of Sales | (17,475,517) | (12,797,064) |
36.56%
|
| Gross Profit | 4,719,390 | 3,730,892 |
26.49%
|
| Distribution Cost | (635,693) | (357,822) |
77.66%
|
| Other Income | 289,575 | 28,263 |
924.57%
|
| Finance Cost | (263,838) | (164,504) |
60.38%
|
| Profit After Taxation | 3,694,209 | 3,001,247 |
23.09%
|
Profit before taxation climbed 26.83% to Rs3.61 billion. Following a reduced taxation credit of Rs87.89 million—down 44.31% from the Rs157.82 million recorded last year—and a minor foreign currency translation loss of Rs0.48 million, the company secured a total comprehensive income of Rs3.69 billion.
Consequently, basic earnings per share (EPS) increased by 14.49% to Rs0.474, while diluted EPS rose to Rs0.473 for the quarter.